US stock markets opened the week with confident gains. The broad-market S&P 500 added 0.7%, the tech-heavy Nasdaq Composite rose 1.1%, and the blue-chip Dow Jones advanced 146 points
US stock markets opened the week with confident gains. The broad-market S&P 500 added 0.7%, the tech-heavy Nasdaq Composite rose 1.1%, and the blue-chip Dow Jones advanced 146 points. The main trigger for the local rebound was renewed buying in AI-related names after a landmark announcement: developer Anthropic has officially filed for an initial public offering (IPO).
Anthropic's listing will be the first large-scale test of retail and institutional appetite for a company focused exclusively on building advanced foundational AI models. As part of the offering, some existing shareholders plan to sell stakes, which will help gauge real market demand for the sector after a string of sell-offs. The news sparked a rally in the semiconductor segment:
Among the heavyweights, Tesla showed notable strength, its stock surging 5.2% after Barclays upgraded the name to Overweight from Equal Weight. At the same time, Meta fell 1.9% as investors were unsettled by the company's plan to raise up to $95 billion through additional share sales to fund AI capital expenditures. Trading across tech names was nervous ahead of imminent earnings: Alphabet lost 1.1%, Amazon fell 0.4%, while Microsoft closed up 1.5%.
One-third of the S&P 500's earnings growth rests on two issuers, and the local lift does not remove the index's core structural concerns. The US stock market faces mounting pressure from two directions:
Until now, Wall Street's rally relied on optimistic forecasts for third-quarter corporate earnings. But a closer look exposes a dangerous vulnerability in the S&P 500 — extreme concentration of expected earnings in a narrow group of issuers. According to Wall Street analysts' calculations, aggregate S&P 500 corporate earnings for Q3 are expected to rise by 30%. More than one-third of that increase is attributable to just two companies — Nvidia and Micron. Expanding the sample to the top ten corporations (including Broadcom and Meta Platforms) shows that they account for two-thirds of the benchmark's projected earnings growth.
A significant contribution outside tech comes mainly from oil and gas giants, which directly benefit from the surge in hydrocarbon prices. The financial metrics of the other 490 S&P constituents are growing much more modestly — on average about 10%. For a bull market entering its fifth consecutive year, this is a respectable rate, but it also highlights how fragile the index's overall foundation becomes if the leaders stumble.
Investors recognize that big-tech super-profits cannot grow exponentially forever. AI infrastructure projects are increasingly dependent on borrowed funds. Against this backdrop, persistently high US Treasury yields directly hit margins — interest expenses on debt rise, compressing corporate net income. The Q3 earnings season is meant to provide a clear answer: do AI capital expenditures generate real cash flow, or should portfolio managers aggressively trim allocations to tech giants?
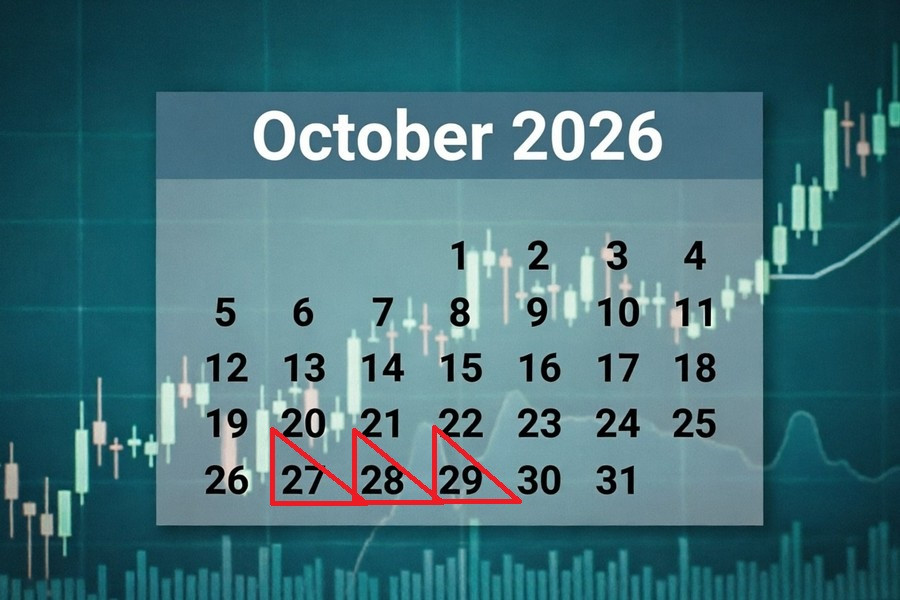
The final week of October carries the greatest destabilization risk for the S&P 500. Traders are focused on the earnings of heavyweights — Microsoft, Alphabet and Amazon. The publication of financial results coincides with meetings of major central banks, the most important being the Federal Reserve. Any hawkish turn from Fed Chair Kevin Warsh could trigger a new wave of selling in the bond market, pushing Treasury yields higher and directly striking tech sector valuations.
Bank of America strategists estimate that the risk-off regime is likely to persist into December. The upside space for the S&P 500 is tightly limited by a complex set of headwinds:
An additional source of nervousness is the upcoming US midterm elections. Wall Street watches with concern the prospect of a Democratic victory. A shift in legislative control to the opposition would block the administration's plans for tax cuts and deregulation, introduce new regulatory hurdles and increase pressure on corporate profit growth.
October 27, 17:00 / US — New-home sales in September / prev.: 643k / act.: 684k / forecast: 650k / USDX (6-currency USD index) — down
August single-family new-home sales in the US showed a strong jump of 6.4%, reaching the highest level since the start of the year despite higher mortgage rates. The main driver was the Midwest, where signed contracts surged nearly 85%, which, together with moderate growth in the South, fully offset weaker buying activity in the Northeast and West. The overall pool of unsold new homes stood at 8.5 months of supply, with the median price of properties rising slightly to $393,700. The September report embeds a notable cooling of demand in the primary housing market. Slower sales growth will put pressure on the US dollar.
October 27, 17:00 / US — Richmond Fed manufacturing index (leading) for October / prev.: 4 / act.: -2 / forecast: 1 / USDX (6-currency USD index) — up
Business activity in the manufacturing sector of the Fifth Federal Reserve District slipped into contraction in September for the first time in six months. The indicator's fall to -2 points was accompanied by simultaneous declines in actual shipments and new orders, as well as a further reduction in the backlog of unfinished contracts. The only positive sign was a local pickup in the employment component, while management caution on investment and inventories lowered expectations for business conditions over the next six months. Analysts expect the activity indicator to return to positive territory in October. The anticipated regional production recovery would support the greenback.
October 27, 23:30 / US — API crude oil inventories / prev.: -11.12M bbl / act.: -4.93M bbl / forecast: — / Brent — volatile
The latest industry report from the American Petroleum Institute recorded continued large withdrawals from US commercial crude stocks: for the week to October 16, inventories fell by nearly 5 million barrels, accompanied by concurrent declines in gasoline and distillate stocks. An additional factor compressing supply was a drop in domestic daily production by 300,000 barrels, while the Cushing hub saw a modest inflow. The lack of an official forecast and the contrast between steep fuel stock draws and crude accumulation at a key delivery node mean the report could increase volatility in Brent futures.
October 28, 03:30 / Australia — Consumer Price Index (CPI) for September / prev.: 3.5% / act.: 4.0% / forecast: 4.2% / AUD/USD — up
Australian consumer inflation jumped sharply to 4.0% in August, reaching a three-month high and settling well above the Reserve Bank of Australia's target range. The key impulse came from transport costs, which soared to 5.6% due to higher motor fuel prices and the end of temporary government fuel excise relief, and from the housing sector, where price growth reached 5.7%. Meanwhile, core inflation measures held at 3.6%, confirming broad price pressure across the consumption basket. The September release is expected to show further acceleration in consumer prices. Stronger inflationary pressure will reinforce expectations of continued tight monetary conditions and support the Australian dollar.
October 28, 10:00 / Germany — GfK consumer sentiment index for November (leading) / prev.: -26.8 / act.: -30.6 / forecast: -31.0 / EUR/USD — down
The leading indicator of consumer sentiment in Germany fell to its lowest levels since late spring. The main driver of deterioration was a sharp 16.7-point drop in household income expectations amid concerns about a new wave of energy price rises. Households' turn toward strict saving pushed propensity to save to levels not seen since the 2008 crisis, paralyzing willingness to spend despite a moderately positive assessment of the economy's general condition. The November consensus expects the sentiment indicator to slip further. Deepening consumer pessimism will weigh on the euro.
October 28, 17:00 / US — Wholesale inventories for September / prev.: 1.4% / act.: 0.5% / forecast: 0.4% / USDX (6-currency USD index) — down
The pace of wholesale inventory accumulation in the US slowed noticeably in August, although continuous stockbuilding has now persisted for seven consecutive months. Supply structure showed marked differentiation: gains in metals and automotive components were offset by declines in computer equipment, while among short-life goods outflows of petroleum products and pharmaceuticals were compensated by inflows of agricultural goods. In September, experts expect further deceleration in wholesale inventory growth. Slower warehouse turnover and business caution will put pressure on the US dollar.
October 28, 16:45 / 17:30 / Canada — Bank of Canada rate decision and press conference / prev.: 2.25% / act.: 2.25% / forecast: 2.50% / USD/CAD — down
The Bank of Canada's September meeting ended with the overnight policy rate held at 2.25%, in line with most market expectations, but the tone of the accompanying statement shifted noticeably toward tightening. The central bank noted an overall improvement in economic activity in Q2 and emphasized domestic resilience to external shocks caused by escalation in the Middle East. At the same time, the regulator signaled heightened concern about inflationary risks tied to sustained high energy prices, rising yields on Canadian government bonds, and the threat of renewed tough trade measures from the US. While core price indicators are still near target, monetary authorities openly flagged the possibility of action if price pressures intensify further. The upcoming decision embeds a rate-hike scenario by the Canadian regulator. Expectations of a tightening bias will provide significant support to the Canadian dollar.
October 28, 17:30 / US — EIA crude oil inventories / prev.: -8.557M bbl / act.: -3.061M bbl / forecast: -0.300M bbl / Brent — up
The US Energy Information Administration's weekly report recorded another sizable drawdown in commercial crude oil stocks: inventories for the week through October 16 fell by more than 3 million barrels, well ahead of analysts' preliminary estimates. The move was driven by active draws of nearly 3 million barrels of gasoline inventories amid a modest increase in refinery throughput, which fully offset a local inflow to storage at the Cushing distribution hub and a rise in distillate inventories. The physical balance of the domestic market remained tight despite net imports of hydrocarbons increasing by 837 thousand barrels per day. In the latest report, analysts expect the trend of declining crude stocks to continue. Continued depletion of commercial inventories will support Brent prices.
October 28, 21:00 / 21:30 / US — FOMC interest rate decision and press conference / prev.: 3.75% / act.: 4.00% / forecast: 4.00% / USDX (6-currency USD index) — up
Statements from Federal Reserve leadership have confirmed the regulator's strong commitment to fighting inflationary pressures. Although Fed Chair Warsh refrained from explicit hints about upcoming decisions at the IMF summit, his assessment of the macroeconomic picture signaled readiness to keep monetary policy tight amid uncomfortably high inflation. After last month's hike of the federal funds rate into the 3.75–4.00% range — the first such step since 2023 and unanimously supported by committee members — markets continue to price in elevated borrowing costs. The coming decision is expected to hold the rate at this high level. Confirmation of a hawkish monetary stance will support the US dollar.
October 29, 02:01 / United Kingdom — Motor vehicle production for August / prev.: -1.2% / act.: -10.6% / forecast: -8.0% / GBP/USD — down
August data for the UK automotive industry reflected a local recovery in passenger-car output, which rose 6.1% and temporarily offset a deep July slump. The increase was supported by domestic demand and higher exports to the US, Japan and Australia, while the key European market, accounting for more than half of UK shipments, fell 7.4%, and exports to China declined 15%. Despite large investments from major automakers, industry association SMMT expressed serious concerns about European protectionist initiatives under a "Made in Europe" program that could limit UK access to the EU market. The upcoming report assumes the sector will remain in decline. Rising regulatory and trade barriers for UK manufacturers will weigh on the pound.
October 29, 15:30 / Canada — Wages for August / prev.: 3.30% / act.: 3.39% / forecast: 3.20% / USD/CAD — up
Average wage growth in Canada continues to hold above the long-term historical norm of around 2.5%. Wage resilience supports domestic consumer demand, offsetting some of the impact of higher borrowing costs on household budgets. The consensus for the August report expected a slowdown in wage growth. Cooling wage dynamics would reduce pro-inflationary pressure and weigh on the Canadian dollar, pushing USD/CAD higher.
October 29, 15:30 / US — Q3 GDP (preliminary) / prev.: 2.5% / act.: 2.2% / forecast: 3.2% / USDX (6-currency USD index) — up
The US economy showed a solid 2.2% increase in Q2, reflecting notable improvement after revisions to private investment, government spending and consumer activity. Key growth drivers were investment in commercial real estate and data centers for the IT industry, as well as rental and financial services — more than offsetting weaknesses in warehouse logistics and retail. Analysts expect a significant acceleration of economic growth in Q3. Broad expansion of business activity would provide strong support for the US dollar.
October 29, 15:30 / US — GDP deflator for Q3 / prev.: 3.7% / act.: 3.6% / forecast: 6.4% / USDX (6-currency USD index) — up
The US GDP price deflator reflects a strong rise in price pressure across the structure of national production, substantially outpacing earlier periods against the backdrop of high commodity and intermediate goods prices. Persistent growth in this broad price indicator confirms active pass-through of increased production costs to consumers and businesses. Markets expect a sharp rise in the deflator in Q3. Heightened price pressure across the economy raises the likelihood of continued tight monetary policy, supporting the greenback.
October 29, 15:30 / US — Personal income for September (m/m) / prev.: 0.2% / act.: 0.3% / forecast: 0.2% / USDX (6-currency USD index) — down
Personal income grew modestly by 0.2% in August, reflecting a gradual slowdown in household inflows. The main increase came from compensation in the private sector and government social transfers, while real disposable incomes adjusted for inflation showed no growth, indicating stagnation in households' purchasing power. The September forecast anticipates continued muted income growth. Slower household income dynamics will weigh on the US dollar.
October 29, 15:30 / US — Personal spending for September (m/m) / prev.: 0.1% / act.: 0.9% / forecast: 0.5% / USDX (6-currency USD index) — down
US consumer spending posted a strong increase in August, rising by nearly $191 billion and marking the strongest expansion since spring. Main drivers included higher spending on motor fuel and energy, everyday goods, and services such as dining and healthcare, supporting real consumption even after accounting for prices. The September release is expected to show a notable cooling of consumer activity. Slower household spending will put pressure on the US dollar.
October 29, 15:30 / US — Initial jobless claims / prev.: 200k / act.: 190k / forecast: 200k / USDX (6-currency USD index) — down
Initial claims for unemployment insurance in mid-October fell to the lowest levels in three months, confirming labor market resilience amid high corporate profitability. Employers remain cautious about staff reductions despite geopolitical tensions in the Middle East, trade policy uncertainty and rising energy costs, although a modest increase in continuing claims points to longer re-employment periods for those losing jobs. The upcoming report expects initial claims to start rising. Early signs of weakening labor market parameters would put pressure on the US dollar.
October 29, 15:30 / US — Personal consumption expenditures (PCE) price index for September / prev.: 3.7% / act.: 3.4% / forecast: 3.6% / USDX (6-currency USD index) — up
Headline PCE inflation in August stabilized at previous levels and came in below market expectations. Core PCE, which excludes volatile food and energy categories, held steady at 3.0%. Nevertheless, the Fed's preferred inflation gauge has consistently exceeded the 2% target since 2021, indicating persistent structural price rigidity in the consumer basket. The September release is expected to show renewed acceleration in core inflation. A pickup in the core index would strengthen arguments for maintaining a tight monetary stance, supporting the US dollar.
October 29, 16:15 / 16:45 / Eurozone — ECB rate decision and press conference / prev.: 2.40% / act.: 2.65% / forecast: 2.65% / EUR/USD — up
September's move by the European Central Bank marked the first rate increase since 2023, reflecting the predominance of upside inflation risks for the bloc. The ECB chose to avoid overly hawkish guidance on the future path of borrowing costs, preserving room for maneuver amid geopolitical uncertainty from the Middle East conflict and hostilities in Eastern Europe. While the current deposit rate was assessed as roughly neutral, the bank confirmed readiness to act in line with the scale of price pressures. Consensus expects the policy rate to remain at a high level in the upcoming decision. Continued tight financial conditions in the currency bloc will support the euro.
October 28, 17:30 / Canada — Speech by Bank of Canada Governor Tiff Macklem / USD/CAD
October 28, 21:30 / US — Speech by Fed Chair Kevin Warsh / USDX
October 29, 16:45 / Eurozone — Speech by ECB President Christine Lagarde / EUR/USD
October 29, 20:50 / Eurozone — Speech by ECB Executive Board member Piero Cipollone / EUR/USD
Speeches by senior central bank officials are also scheduled during these days. Their comments typically stir volatility in currency markets as they may signal future policy intentions.
QUICK LINKS
ForexMart is authorized and regulated in various jurisdictions.
(Reg No.23071, IBC 2015) with a registered office at First Floor, SVG Teachers Co-operative Credit Union Limited Uptown Building, Corner of James and Middle Street, Kingstown, Saint Vincent and the Grenadines
Restricted Regions: the United States of America, North Korea, Sudan, Syria and some other regions.


 Contact Us