EUR/USD started November with a gain: on Monday the euro rose about 0.5% to 1.1237 after closing last week at 1.1160. That is a notable bounce after the pair
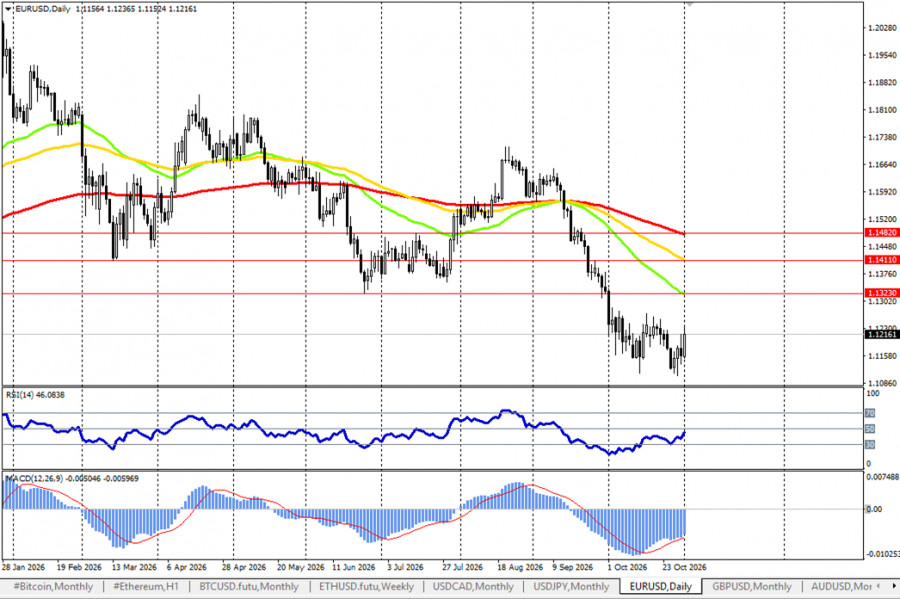
EUR/USD started November with a gain: on Monday the euro rose about 0.5% to 1.1237 after closing last week at 1.1160. That is a notable bounce after the pair hit a year low of 1.1104 on October 29. But does it signal a reversal? Judging by the fundamental picture, not yet: the rise is explained by lower oil prices and position-squaring ahead of U.S. elections, while the euro's main problems remain.
What supported the euro on Monday?
The primary factor was oil. Brent fell roughly 3% to $110 a barrel after Qatar-mediated talks between Iran and the U.S. continued. Media reports say U.S. President Donald Trump promised not to strike before the midterms, although he did not rule out action afterward. For the eurozone, which imports most of its energy, lower oil eases the stagflation threat.
The second reason was positioning. Ahead of the vote, major investors trimmed dollar longs, and U.S. Treasury yields eased slightly. Market participants view this more as a tactical rebound from position-covering than a change in trend. AMINA Bank notes that hedge funds suffered heavy losses in October, leaving the market limited scope to absorb surprises.
Eurozone data: better than expected, but no turning point
Recent data were mixed but broadly in line with forecasts. Eurozone GDP grew 0.4% in Q3 versus expectations of 0.2%, while unemployment held at 6.5%. German inflation slowed to 2.8% in October from 3.3%—below expectations—largely thanks to a temporary cut in fuel tax. Core inflation in Germany eased to 2.1%.
The country picture is uneven. France's economy contracted 0.1% in Q3, Italy recorded no growth, and Italy's inflation jumped to 5.4% in October. Slowing German inflation reduces the case for an ECB hike in December, which limits support for the euro.
France: Fitch downgrades outlook
On Friday Fitch revised France's sovereign outlook from stable to negative. Moody's had already kept a negative outlook. The spread between French and German 10-year yields widened by 9 basis points to 165 amid ongoing protests, and French 10-year yields trade around 4.97%. France's public debt stands at 119% of GDP, the 2027 budget remains unsigned, and candidates from fringe parties lead opinion polls ahead of spring presidential elections.
ECB: Uncertainty persists.
On October 29 the ECB left the deposit rate at 2.50% and noted that financial conditions have tightened. ECB President Christine Lagarde announced she will step down on February 7, 2027; a successor is not yet named. The market expects an ECB hike in December, but slowing German inflation and rising French yields make that call less clear.
US: elections and the labor market
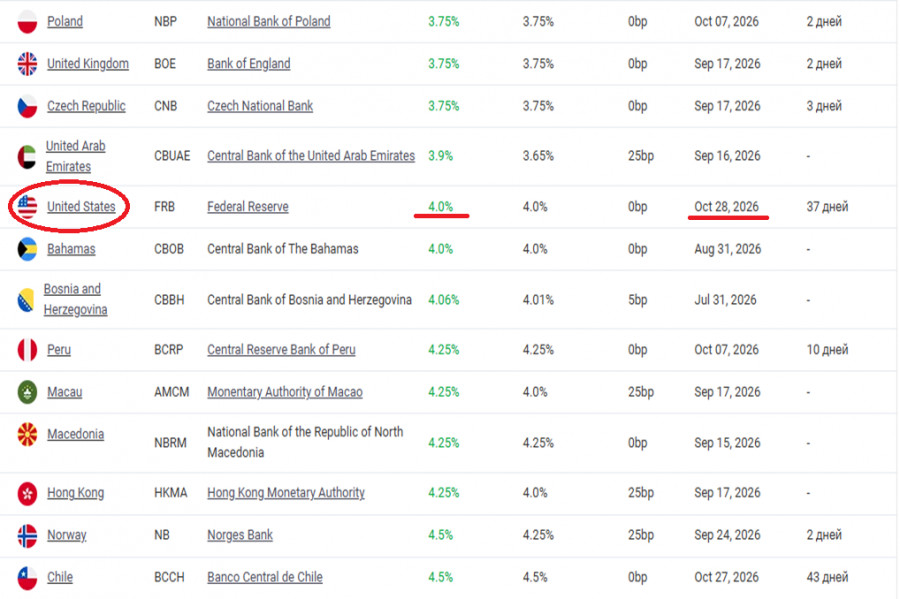
The Fed on October 28 kept rates at 3.75–4.00% with two votes for a hike. U.S. Q3 GDP rose 3.4% annualized; the employment cost index increased 3.4% year over year. The market still puts a higher probability on a Fed hike at the December 8–9 meeting.
This week the focus is on two events. November 3 is the midterm election. Forecasts give Democrats a high probability of winning the House, while the Senate race is less certain. Standard Chartered warns that polls show strong anti-incumbent sentiment, which does not always translate into results. On November 6 the U.S. jobs report for October will be released: a strong print would reinforce expectations for a December Fed hike.
Rate differential
The gap between the Fed's upper rate (4.00%) and the ECB deposit rate (2.50%) is 150 basis points. If the Fed hikes in December while the ECB pauses amid slowing German inflation, the gap could widen to 175. The current euro bounce does not change this factor.
What could alter the picture
In support of the euro:
- continued drops in oil and progress in Middle East talks;
- US election results that increase fiscal uncertainty and weaken the dollar;
- a weak U.S. jobs report on November 6 that reduces Fed tightening odds;
- adoption of the French budget.
Against the euro:
- strong US labor or inflation data;
- renewed strikes in the Middle East after the elections and higher oil prices;
- further deterioration in France and widening spreads;
- The ECB is shelving a December hike amid slowing inflation.
Technical picture: a retracement toward resistance
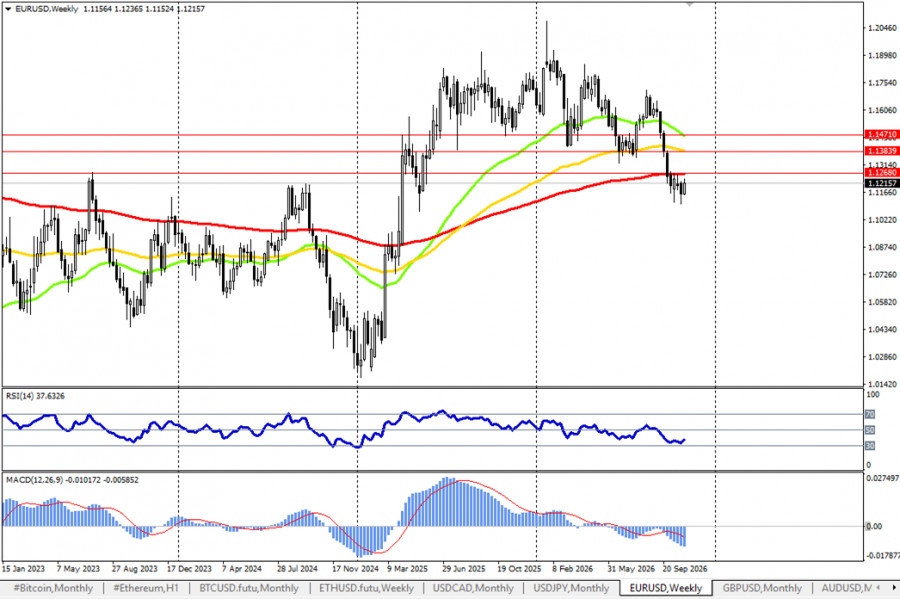
On the daily chart the pair remains in a downtrend: the price is below EMA 50 (1.1323), EMA 100 (1.1411), and EMA 200 (1.1482). On the weekly chart, the price sits below the weekly EMA 200 (1.1268). The current rise is a retracement that relieves oversold conditions. Key resistance lies in the 1.1268–1.1272 zone, where the weekly and four-hour EMA 200 converge and which marks the upper bound of the October range. Support is at 1.1171–1.1181, then the year low at 1.1104.
Conclusion
Monday's euro gain is a pause, not a reversal. It was driven by falling oil and position-squaring ahead of the vote, while the main downward pressures remain: France's twin negative outlooks, ECB leadership uncertainty, and a rate differential that favors the dollar.
Buying the euro from current levels bets on further oil weakness and disappointing U.S. data. Selling it ignores that the pair has not yet reached strong resistance and that the market is closing positions ahead of the election.
Key week: U.S. midterms on November 3 and the U.S. jobs report on November 6. If the retracement reaches 1.1268–1.1272 and strong U.S. data confirm a hawkish Fed path, pressure on the euro will resume. Until then—wait and see.
This material is informational and analytical and does not constitute individual investment advice.
LINKS RÁPIDOS
ForexMart is authorized and regulated in various jurisdictions.
(Reg No.23071, IBC 2015) with a registered office at First Floor, SVG Teachers Co-operative Credit Union Limited Uptown Building, Corner of James and Middle Street, Kingstown, Saint Vincent and the Grenadines
Restricted Regions: the United States of America, North Korea, Sudan, Syria and some other regions.


 Contate-nos