The announced resignation of Christine Lagarde has effectively overshadowed the ECB's October meeting. Even so, the monetary policy gap remains the more important factor for EUR/USD
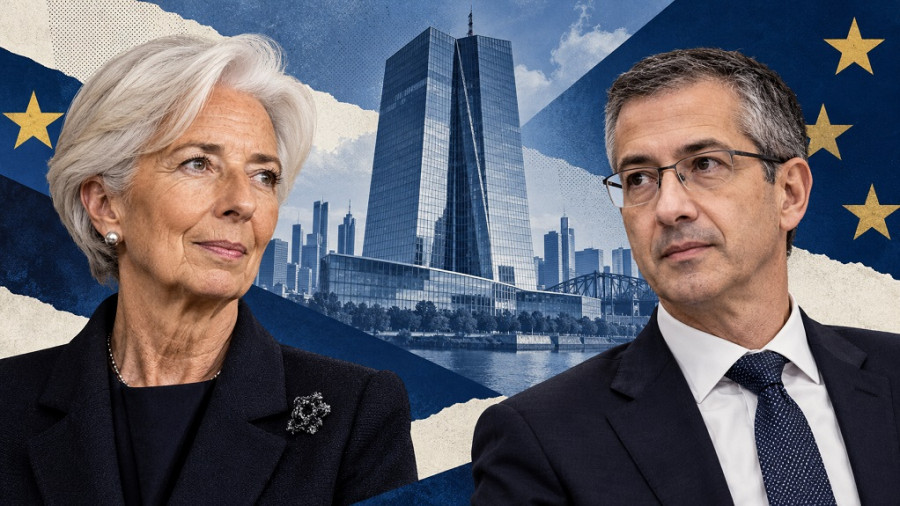
Yesterday, we learned that ECB president Christine Lagarde will leave office early—on February 7, 2027. The news was not exactly a bombshell. Talk of a possible early exit began back in February when the Financial Times linked her departure to the upcoming French presidential election.
At that time, the ECB reacted cautiously to the newspaper rumors, saying Lagarde was focused on her work and had made no decision to step down. In essence the regulator neither confirmed nor denied the reports. Later Lagarde herself acknowledged the possibility of an early departure but gave no specifics. Over time the story faded to the second or third tier and then died down.
So, yesterday's statement sounded both unexpected and, in a sense, predictable.
The political subtext is fairly transparent. France faces presidential elections next spring that could significantly complicate Paris's ties with Brussels. One likely scenario is a second round between far-right Marine Le Pen and radical leftist Jean-Luc M-lenchon. According to Reuters, Le Pen currently leads polling. While it is premature to declare any candidate certain, the odds are high that the winner will come from one of the two poles—right or left.
An early departure by Lagarde allows the successor to be agreed upon while Emmanuel Macron is still president, preserving the influence of the current French administration over the staffing decision. That is important because the appointment is for eight years. You could say Lagarde is "playing along" with Brussels by helping to pre-empt a potentially contentious issue. Although she frames her resignation as a desire to "speak more freely on issues beyond monetary policy," the political motives are obvious.
Against that backdrop, the key question is who will succeed Lagarde as ECB president. The names most frequently mentioned are former Dutch central bank head Klaas Knot and former Bank of Spain governor Pablo Hernandez de Cos, who now heads the Bank for International Settlements. De Cos looks the most likely candidate, including in a Bloomberg poll published last week: 12 economists named him, while nine named Knot. In Spain de Cos enjoys support from both Prime Minister Pedro Sanchez and opposition leader Alberto Nunez Feijoo.
It is also notable that Spain has never had an ECB president, and appointing a hawk like Boris Vujcic as vice chair could bolster the position of a more moderate candidate such as de Cos.
What to expect under his leadership? Many analysts characterize Knot as a "pragmatic hawk," while de Cos is seen as more dovish. Yet both nominees are expected to preserve policy continuity at the ECB.
In my view, de Cos will pay more attention to the risks of over-tightening and will try to balance the fight against inflation with support for growth. But do not expect the ECB to cut rates immediately on his arrival; decisions remain the remit of the Governing Council, and the president's role is to organize debate, help forge consensus, and convey the bank's collective position to markets. Certainly the president's influence goes beyond a single vote, but the chair cannot unilaterally set policy. That said, in the event of a tie the president's view can be decisive.
Yesterday's personnel story effectively eclipsed the ECB's October meeting, which turned out to be uneventful. The regulator left rates unchanged and used well-worn language. On the one hand the ECB kept open the possibility of a rate hike in December; on the other it stressed relative stability of core inflationary pressures and the absence of a meaningful pickup in wage growth. Tighter financial conditions were another restraining factor. Overall the bank had to weigh the risk of entrenched high inflation against the risk of excessively cooling domestic demand.
Reacting to yesterday's events, EUR/USD retreated from lows but failed to secure a firm foothold back in the 1.12 area. I view this rise primarily as a correction amid broader dollar weakness and a temporary euro boost from the ECB's still-priced-in December hike. However, the ECB did not toughen its stance further, so there is no basis for a sustained euro appreciation.
US macro reports yesterday were, conversely, dollar-friendly: US Q3 GDP rose 3.4% y/y (forecast 3.2%), and personal consumption rose 3.8%. Strong demand accompanies accelerating inflation, allowing the Fed not only to maintain a hawkish stance but to toughen it further.
Thus, I still see the dollar as having the upper hand. Both central banks—the Fed and the ECB—could tighten further at their December meetings. But the Fed rests on firmer domestic demand, while the ECB must factor in rising risks of economic slowdown. A change of ECB president will not eliminate that difference. Therefore, the euro pullbacks should be regarded as shorting opportunities, with a primary target at 1.1130 (the lower Bollinger Band on D1).
ForexMart is authorized and regulated in various jurisdictions.
(Reg No.23071, IBC 2015) with a registered office at First Floor, SVG Teachers Co-operative Credit Union Limited Uptown Building, Corner of James and Middle Street, Kingstown, Saint Vincent and the Grenadines
Restricted Regions: the United States of America, North Korea, Sudan, Syria and some other regions.


 আমাদের সাথে যোগাযোগ করুন