Preparing for the US midterms has entered the home stretch: reserved ad budgets and parties' direct campaign spending are hitting record highs. But the week's main political shock came from
Preparing for the US midterms has entered the home stretch: reserved ad budgets and parties' direct campaign spending are hitting record highs. But the week's main political shock came from Frankfurt. ECB President Christine Lagarde has officially announced she will step down early on 7 February 2027 — nine months before her term was due to end. The unexpected departure opens a sharp behind-the-scenes battle for the central bank's top job just as the bloc faces a fresh wave of inflationary pressure. Leading candidates for the vacant post include:
Analysts note that the accelerated timetable for the resignation has a political dimension: the new chair will be appointed before France's presidential election in the spring, allowing the incumbent government of Emmanuel Macron to lock in its preferred successor. The euro was the chief casualty of Thursday's trading session, weakening against most major currencies. Selling intensified after the ECB left the deposit rate unchanged at 2.50%. The regulator acknowledged the risks of a prolonged energy shock to prices and growth but pointed to:
That decision disappointed markets that had priced a 76% chance of policy tightening in December and further hikes through the year. The Governing Council's statement was notably cautious and triggered a synchronous fall in euro-area sovereign yields.
US macroeconomic data showed resilience, yet the market met them with surprising calm. US GDP growth for Q3 accelerated sharply to 3.4% year-on-year from 2.2% in the prior quarter, beating Wall Street consensus. The PCE inflation index rose to 3.6% in September from 3.4% in the previous month. Real final sales to private domestic purchasers jumped to 4.9%, confirming the strength of underlying local demand.
However, a closer read revealed hidden pockets of weakness. Real consumer spending in September was essentially flat, while real disposable income fell 0.3%. The monthly core PCE index came in exactly at expectations (0.3%), so traders had no cause for panic. US market reactions were muted:
The probability of a Fed rate hike in December was revised to 83% (from 85% a day earlier). Recall that the Fed yesterday left the policy rate range at 3.75%–4.00%, with two policymakers voting for an immediate increase. Markets had already priced in a December hike, so the macro print did not trigger a sharp re-pricing of rate expectations. Treasury yields remained stable, confirming there was no panic flight into risk-free government debt. Pressure was contained within a segment of Wall Street equities without spilling over into bond or FX markets.
Meanwhile, investment in AI has become a core pillar of US economic growth: current expert estimates suggest the factor generates up to one-third of aggregate GDP gains. Estimates of AI's direct contribution to US economic growth in 2026 vary:
Three interconnected mechanisms drive the effect: direct corporate capital spending by tech firms, a construction boom in data centres, and a pronounced "wealth effect." Big tech market-cap gains boost the wealth of affluent households, supporting their consumption (this channel may account for up to half of AI's overall macro impact).
However, excessive dependence of the US economy on a single technological theme creates a structural vulnerability. Any cooling of the investment boom or a prolonged correction in tech stocks would directly hit commercial construction, consumer spending and hiring in related sectors, while the real effect of AI on aggregate labour productivity in the economy remains uncertain.
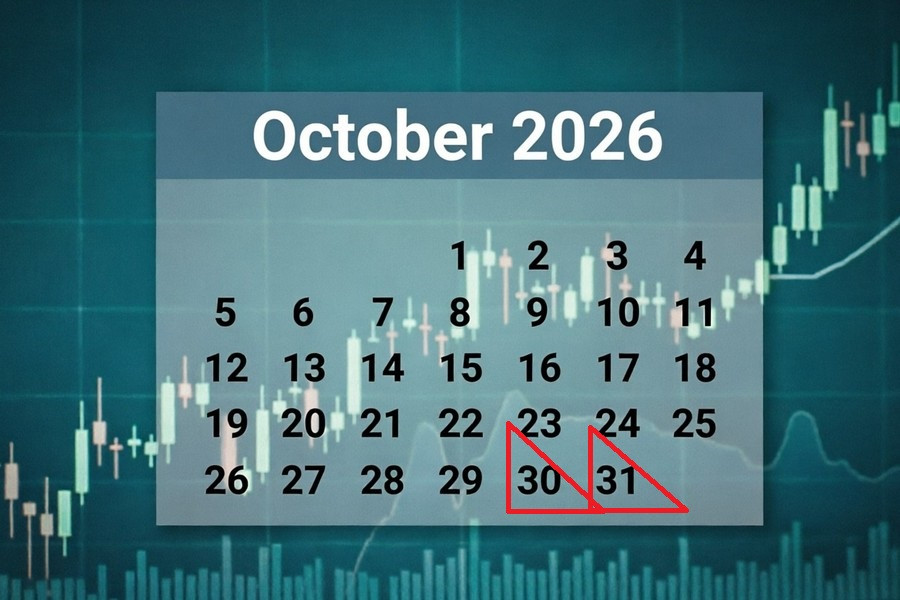
October 30, 02:50 / Japan / Retail sales (Sep) / prev: 3.7% / actual: 2.7% / consensus: 3.3% / USD/JPY – down
August retail sales in Japan rose 2.7% year-on-year, extending a six-month growth streak helped by government measures to contain prices. The auto sector was the main locomotive of consumer activity, with vehicle sales jumping 17.7%, while non-store retail and department stores also supported spending, partially offsetting weaker outlays on:
A 1.2% monthly correction in trade turnover merely adjusted a strong July rise, leaving the overall consumer trend intact. Analysts expect retail sales dynamics to accelerate in September. A pickup in household spending would support the Japanese yen.
October 30, 02:50 / Japan / Industrial production (Sep) / prev: 3.9% / actual: 2.7% / consensus: 3.1% / USD/JPY – down
Japan's industrial production posted a 2.7% year-on-year increase for August, recording a moderate slowdown in activity after stronger July results. Although current output remains below long-run historical norms, the sector retains positive momentum amid a difficult global environment and logistical constraints.
Consensus forecasts expect industrial production to pick up in September. A revival of factory activity would bolster the yen.
October 30, 03:30 / Australia / Producer price index (PPI) q/q (Q3) / prev: 0.4% / actual: 1.3% / consensus: 1.0% / AUD/USD – down
Wholesale inflation in Australia surged 1.3% q/q in Q2, the biggest quarterly jump since autumn 2023. The main driver was refineries, which leapt 37.5% amid a global oil rally tied to Middle East tensions, while heavy construction and residential rental costs also contributed, more than offsetting seasonal declines in accommodation services.
Analysts expect wholesale inflation to decelerate in Q3. Easing price pressures on businesses would weigh on the Australian dollar.
October 30, 03:30 / Australia / Producer price index (PPI) y/y (Q3) / prev: 3.0% / actual: 3.6% / consensus: 4.5% / AUD/USD – up
Australia's annual PPI accelerated to 3.6% in Q2, the highest reading since early 2025 and well above the long-term average of around 2.5%. Persistent rises in production costs highlight the deep penetration of commodity shocks throughout value chains.
Analysts expect a further acceleration of wholesale inflation in the next release. Rising price pressure in the production segment would strengthen expectations for tighter monetary policy and support the Australian dollar.
October 30, 06:00 / 09:30 / Japan / BOJ policy decision and press conference / prev: 1.00% / actual: 1.25% / consensus: 1.25% / USD/JPY – volatile
September's Bank of Japan decision raised the policy rate to 1.25%, the highest borrowing cost since spring 1995. The step was taken by majority vote amid mounting inflationary pressure and external calls from U.S. monetary authorities, shortening the interval between tightening rounds to a record three months. Despite dissent within the board, the bank signalled the likelihood of inflation staying above the 2% target for an extended period and potentially approaching 3%.
The forthcoming decision is expected to keep the policy rate at the elevated level. A sustained hawkish stance and the BOJ's readiness to combat persistent price rises would support the yen.
October 30, 10:00 / Germany / Import price index (Sep) / prev: 6.8% / actual: 8.3% / consensus: 10.3% / EUR/USD – up
Germany's import prices posted a sharp increase in August, reaching the highest level since late 2022 as a fresh round of Middle East tensions pushed up energy costs. Purchases of electricity and oil products rose more than 60%, while natural gas and crude oil climbed 30–40%. At the same time, the rally in non-ferrous metals lifted intermediate goods prices, more than offsetting moderate declines in consumer import prices.
Consensus expects import price growth to accelerate further in September. Rising imported inflationary pressure would bolster the case for a continued tight monetary stance and support the euro.
October 30, 10:00 / UK / Nationwide house price index (Oct) / prev: 1.6% / actual: 0.8% / consensus: 0.6% / GBP/USD – down
UK house prices in September recorded the sharpest slowdown since late last year, reflecting subdued buyer activity amid geopolitical uncertainty and expensive borrowing. Although moderate wage growth in the private sector is gradually improving affordability relative to incomes, elevated mortgage rates are suppressing demand, causing a 0.2% monthly fall in prices.
Analysts expect further cooling in October. Continued weakness in the housing market would weigh on the pound.
October 30, 11:55 / Germany / Change in unemployment (Oct) / prev: 5k / actual: 12k / consensus: 5k / EUR/USD – up
Germany's unemployment rose more than twice the August level in September, exceeding long-run averages amid caution in the industrial sector. Still, the labour market remains resilient to external shocks, avoiding large-scale layoffs thanks to government support programs.
Experts expect a sharp slowdown in new unemployment inflows in October. Stabilisation of the labour market in the region's largest economy would support the euro.
October 30, 12:00 / Germany / GDP preliminary (Q3) / prev: 0.7% / actual: 1.0% / consensus: 1.1% / EUR/USD – up
Germany's economy gained momentum in Q2, accelerating relative to the start of the year after upward revisions to preliminary estimates. Although current readings still lag long-term historical averages, Europe's largest economy continues to adapt to higher energy costs and reconfigure supply chains.
Analysts expect growth to continue accelerating in Q3. Stronger macro activity in Germany would support the euro.
October 30, 13:00 / Eurozone / GDP preliminary (Q3) / prev: 0.6% / actual: 1.2% / consensus: 1.1% / EUR/USD – down
The eurozone's economic rebound in Q2 doubled its pace thanks to synchronized household spending recovery, stronger corporate investment and a sharp rebound in goods exports, which rose nearly 4%. The acceleration covered leading economies such as Germany and Italy, with Spain also strong, more than offsetting slower growth in France and restrained public spending.
Markets expect a moderate slowdown in Q3 preliminary estimates. Some cooling of pan-European momentum would weigh on the euro.
October 30, 15:30 / Canada / GDP (m/m) — August / prev: 0.4% / actual: 0% / consensus: 0.2% / USD/CAD – down
Canada's July GDP showed zero monthly growth after a run of solid gains. Stagnation reflected offsetting trends: gains in construction and utilities were offset by declines in manufacturing and oil & gas, while service sector rises in rents, R&D, and hospitality compensated for weaker wholesale and retail trade.
August's report is expected to return the economy to positive growth led by mining and retail. A renewed expansion would strengthen the Canadian dollar.
October 30, 15:30 / US / Social benefits expenditures (Q3) / prev: 1.2% / actual: 1.0% / consensus: 0.7% / USDX (6-currency USD index) – down
Growth in spending on social and compensation benefits for US civil servants slowed to 1.0% in Q2 after a stronger prior period. Corporate sector wage-related costs rose 0.9%, while regional and local government payouts increased 1.1%. A gradual slowdown in personnel-related expenditures signals easing cost pressures from the labour market.
Analysts forecast further moderation in social benefit spending in Q3. Lower labour cost inflation would weigh on the dollar.
October 30, 16:00 / Germany / CPI preliminary (Oct) / prev: 2.9% / actual: 3.3% / consensus: 3.0% / EUR/USD – down
Germany's September inflation accelerated to levels not seen since late 2023 amid a renewed energy-price surge (+14.9%). Major drivers included:
Food prices also rose. Core inflation remained at 2.4%, the services sector slowed moderately, and the harmonised EU measure stayed well above the regional regulator's reference.
Consensus expects a cooling in October's CPI. Slower inflation in the bloc's largest economy would ease expectations of further tightening and weigh on the euro.
October 30, 16:45 / US / Chicago business activity index (Oct) / prev: 47.1 / actual: 58.8 / consensus: 56.1 / USDX – down
The Chicago business activity barometer rebounded strongly in September, returning to expansion with the biggest gain since late spring. A 15.5-point surge in the manufacturing component and seasonal new orders supported continued supplier deliveries amid modest inventory drawdowns. The labour component slipped back into contraction due to staff optimisation and outsourcing, while price pressures, despite local easing, remain a burden for firms.
Analysts expect a moderate pullback in the index in October. Cooling regional activity would weigh on the dollar.
October 31, 04:30 / China / NBS manufacturing PMI (Oct) / prev: 49.8 / actual: 50.1 / consensus: 50.0 / Brent – down, USD/CNY – up
China's official manufacturing PMI moved into expansion for the first time since summer, driven by:
However, the upswing came with rising production costs to five-month highs, falling external orders, continued weakness in employment and subdued business expectations amid high external dependency.
Analysts expect the indicator to return to neutral in October. A manufacturing sector on the edge of stagnation would pressure Brent and push USD/CNY higher.
October 31, 04:30 / China / NBS non-manufacturing PMI (Oct) / prev: 49.0 / actual: 50.2 / consensus: 50.5 / Brent – up, USD/CNY – down
China's non-manufacturing PMI ended a two-month decline in September, returning to growth thanks to a synchronized pickup in construction and services. Strong expansion was recorded in:
This offset persistent property-market and capital-market strains, restoring order books, stabilizing employment, and improving six-month business expectations.
Experts expect further strengthening in services activity. Expansion in construction and services would support commodity demand, lifting Brent and strengthening the yuan.
October 30, 09:30 / Japan / Speech by BOJ Governor Kazuo Ueda / USD/JPY
October 30, 12:00 / UK / Speech by Clare Mills (Bank of England) / GBP/USD
October 30, 16:00 / US / Speech by Mary Daly (President, Federal Reserve Bank of San Francisco) / USDX
October 30, 19:10 / Eurozone / Speech by Philip Lane (ECB Governing Council) / EUR/USD
October 30, 19:30 / US / Speech by Alberto Musalem (President, Federal Reserve Bank of St. Louis) / USDX
Officials from major central banks are also due to speak in the coming days. Their comments typically trigger FX volatility, as they can signal future policy intentions.
ForexMart is authorized and regulated in various jurisdictions.
(Reg No.23071, IBC 2015) with a registered office at First Floor, SVG Teachers Co-operative Credit Union Limited Uptown Building, Corner of James and Middle Street, Kingstown, Saint Vincent and the Grenadines
Restricted Regions: the United States of America, North Korea, Sudan, Syria and some other regions.


 আমাদের সাথে যোগাযোগ করুন